An acquihire is a corporate transaction that brings a startup's team in-house, usually alongside a purchase or license of its technology, instead of buying the business for its product and customers.
The structure matters because the same team can move through a full purchase, a hiring-only arrangement or a licensing package, and both the UK Competition and Markets Authority (CMA) and the European Commission have treated one such talent deal, Microsoft's hiring of Inflection AI's team, as a merger.
What Is an Acquihire?
In an acquihire, the buyer's main purpose is to bring a startup's people, not its product or customers, into the company. The label is informal, not a legal term, and acqui-hire and acqui-hiring are used interchangeably.
- Acquihire (acqui-hire, acqui-hiring)
- A deal whose main value to the buyer is the team. The buyer may purchase or license some of the startup's IP alongside, but it does not take the business as a going concern.
- Reverse acquihire
- An informal industry label for a license-and-hire deal. The buyer hires much of the team and licenses the startup's technology, while the startup continues to exist. It is not a legal term.
- License-and-hire
- A structure that pairs a technology license from the startup with employment offers to its people. The license can be non-exclusive, which leaves the startup free to license the same technology to others.
- Retention package
- The compensation a buyer offers an individual it wants to keep, usually cash or equity that vests over time, set separately from any payment to the startup.
Acquihire vs Acquisition vs License-and-Hire
The acquihire, the full acquisition and the license-and-hire deal differ in what the buyer ends up owning and in what happens to the company left behind. In a full acquisition, as in Cognition's purchase of Windsurf, the buyer takes the IP, product, trademark, brand and business as well as the people, per Cognition. In a license-and-hire deal, such as the Nvidia and Groq agreement, the buyer takes a license and key staff while the startup keeps operating, per Groq. Industry shorthand sometimes calls that second pattern a reverse acquihire, because the buyer leaves the corporate shell, with its customers and investors, behind. The name is shorthand, not a legal term.
| Acquisition | Acquihire | License-and-hire | |
|---|---|---|---|
| What the buyer gets | The whole business: IP, product, brand and people (Cognition and Windsurf) | Mainly the team, with assets bought or licensed as needed | A technology license plus key staff (Nvidia and Groq) |
| The company left behind | Becomes part of the buyer | Set by the deal documents; product and customers may stay behind | Keeps operating as an independent company, per Groq |
| Who joins the buyer | The company's people, with vesting cliffs waived, per Cognition | Selected team members on individual offers | Founders and other team members, such as Jonathan Ross and Sunny Madra, per Groq |
| Typical paperwork | A definitive acquisition agreement | Employment agreements plus an asset purchase or IP assignment | A licensing agreement plus employment offers |
| The merger-filing question | Ordinary merger control; filing depends on notification thresholds | Depends on whether the package is a merger in substance | The same question; the CMA and the Commission treated Microsoft and Inflection as a merger |
Each example column reflects one deal's announced terms. Other deals in the same category set their own terms.
How an Acquihire Deal Is Structured
Most acquihires combine two tracks: a commercial deal with the startup and individual employment offers for the people the buyer wants. The sequence usually runs as follows.
- The buyer identifies a startup whose team holds skills it wants, often in AI research or engineering.
- Talks open under an NDA that covers the startup's technology and staff.
- The parties settle terms for the company deal: an asset purchase, an IP assignment, a subsidiary arrangement or a license.
- Offers go to individuals, each with an employment agreement and a retention package.
- Signing and announcement follow, after counsel has asked whether premerger notification or another merger filing is required before closing.
- Integration moves the hired staff onto the buyer's payroll and equity plan.
The commercial track can take several forms: an asset purchase, an IP assignment paired with employment agreements, a subsidiary arrangement, or a license, according to an explainer from Buzko Legal. The license route is the one behind the Microsoft and Inflection and Nvidia and Groq deals described below.
Payouts to founders, employees and investors follow the deal documents, not a formula, and the startup's financing history (Series A and Series B terms, SAFEs) shapes who is paid first. Cognition describes one such treatment for its own deal: per Cognition, every Windsurf employee participates financially, with vesting cliffs waived and vesting accelerated for work to date. That is how Cognition handled unvested equity in that deal. Other buyers set their own terms.
Well-Known Acquihires and Talent Deals
Three announced deals show the range of acquihire and talent deal structures.
- Microsoft and Inflection AI
- Microsoft announced on March 19, 2024 that Mustafa Suleyman and Karén Simonyan were joining it to form Microsoft AI, with Suleyman as EVP and CEO and Simonyan as Chief Scientist, focused on Copilot and other consumer AI products (per Microsoft). The CMA found that the hiring of former Inflection staff and the associated arrangements, including a non-exclusive licensing deal for Inflection IP, formed a relevant merger situation (CMA summary decision). The European Commission regarded the agreements as a concentration (Commission press release IP/24/4727).
- Nvidia and Groq
- Groq announced on December 24, 2025 a non-exclusive licensing agreement with Nvidia for Groq's inference technology. Per Groq, founder Jonathan Ross, president Sunny Madra and other team members join Nvidia, while Groq continues as an independent company with Simon Edwards as CEO and GroqCloud continues to operate. It is a recent example of the license-and-hire pattern.
- Cognition and Windsurf
- Cognition, the company behind Devin, announced on July 14, 2025 a definitive agreement to acquire Windsurf, including its IP, product, trademark, brand and business as well as its people (per Cognition). It is a full acquisition, but of what remained after a talent deal: three days earlier, on July 11, 2025, Windsurf said co-founders Varun Mohan and Douglas Chen and some members of its R&D team would join Google under an agreement with Google (per Windsurf). The same startup went through both structures within a week.
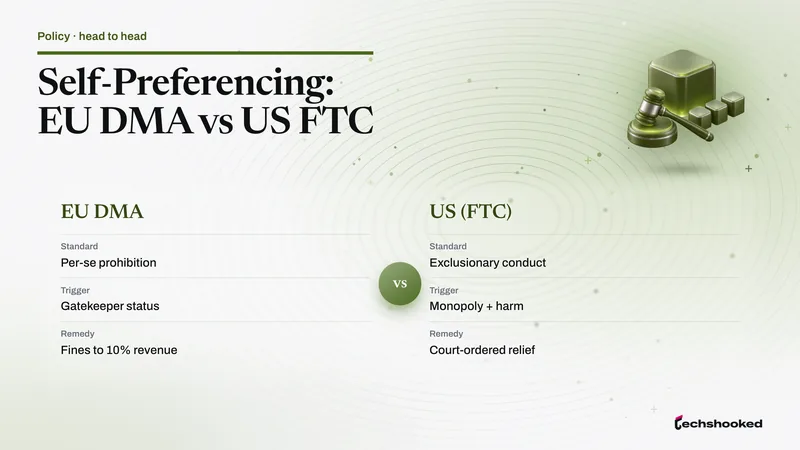
Three deals cannot show how enforcement works across a sector. The wider enforcement picture is covered in the comparison of how US and EU competition authorities approach the largest platforms.
Why Regulators Are Looking at Acquihires
Competition law reviews mergers, not hiring, so the question regulators ask about an acquihire is whether a hiring-plus-license package amounts to a merger in substance. Merger control in each regime looks at what the buyer actually acquires, whatever the deal is called. None of the rules cited below was written for acquihires.
The US Filing Framework
Under the Hart-Scott-Rodino Act, the parties to certain proposed transactions must submit premerger notification to the Federal Trade Commission (FTC) and the Department of Justice (DOJ), and may not close until the waiting period passes or early termination is granted, per the FTC. Merger law is forward-looking and bars transactions that may harm competition, and the FTC and DOJ Merger Guidelines set out the agencies' analytical framework, per the FTC's merger guide. US merger review has no separate acquihire track, so whether a given hiring-plus-license package is a reportable acquisition is a fact-specific legal question. The general review process is laid out in the guide to how regulators decide whether a deal needs a merger review.
UK: A Team With Know-How Can Be a Business
The CMA found that Microsoft's hiring of certain former Inflection employees, together with associated arrangements that included a non-exclusive licensing deal for Inflection IP, was a relevant merger situation, the Enterprise Act 2002 test for CMA jurisdiction. It also found no realistic prospect of a substantial lessening of competition (SLC), per its summary decision, and the CMA case page records the clearance, announced on September 4, 2024. The CMA's summary decision says that acquiring a team with relevant know-how may fall within the CMA's merger control jurisdiction even without further assets, and cites its guidance CMA2, paragraph 4.9, under which an enterprise may include a group of employees and their know-how where that lets a business activity continue. The CMA understood the hires to be almost all of Inflection's team.
EU: Article 22 and the Illumina/GRAIL Ruling
The European Commission regarded the Microsoft and Inflection agreements as a concentration under Article 3 of the EU Merger Regulation (Regulation (EC) No 139/2004). The transaction did not reach the Article 1 notification thresholds and was not notified in any Member State. Seven Member States then submitted Article 22 referral requests, and they withdrew them after the Court of Justice's September 3, 2024 judgment in Illumina/GRAIL, so the Commission took no decision, per its press release IP/24/4727. An Article 22 referral lets Member States ask the Commission to examine a deal without an EU dimension that affects trade within the Single Market and threatens to significantly affect competition in their territory; since Illumina/GRAIL, a Member State can refer only a deal it could review under its own merger rules. As of October 2026, the Commission's case page for M.11671 shows no decision.
Gatekeepers Must Tell the Commission
Article 14 of the Digital Markets Act (Regulation (EU) 2022/1925) obliges a gatekeeper to inform the Commission of any intended concentration within Article 3 of Regulation (EC) No 139/2004 where the merging entities or the target provide core platform services or other digital-sector services, or enable the collection of data. The duty applies whether or not the deal is notifiable under that Regulation or national merger rules, and the information is due after the agreement is concluded and before implementation, per the text on EUR-Lex. The duty falls only on designated gatekeepers. The Digital Markets Act explainer sets out the EU gatekeeper rules that require acquisition notices, alongside the other gatekeeper obligations.
| Authority | Official page | What it says |
|---|---|---|
| FTC | Premerger Notification Program | Parties to certain proposed deals must file and wait before closing; no separate acquihire track |
| CMA | Microsoft / Inflection case page and summary decision | Relevant merger situation; no realistic prospect of a substantial lessening of competition; cleared September 4, 2024 |
| European Commission | Press release IP/24/4727 | Concentration under Article 3; Article 1 notification thresholds not reached; no decision taken |
| Digital Markets Act | Article 14 text on EUR-Lex | Gatekeepers must inform the Commission of intended concentrations, notifiable or not |
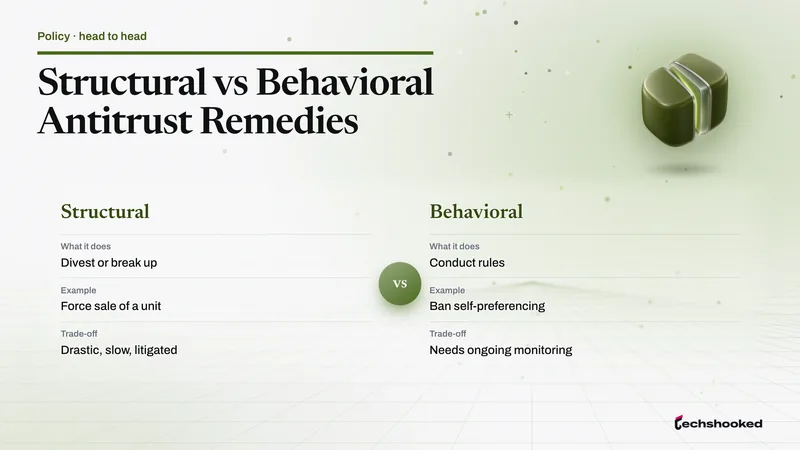
The Microsoft and Inflection review ended in clearance in the UK and no decision in the EU. If a review does find a competition concern, what remedies competition authorities can impose is the next question.
What Founders Should Read in the Term Sheet
A term sheet for an acquihire is worth reading line by line, because the total deal value does not show who is paid, when, or in what form. This section is explanation, not legal advice.
- Proceeds split: how money divides between founders, employees and investors, and how a liquidation preference interacts with a small payout, since preferred holders can be paid before common holders.
- Retention package: its size, its vesting schedule and the conditions attached to each person's offer.
- Unvested equity: whether it is accelerated, cashed out or canceled at closing.
- IP: whether it is assigned or licensed, and whether a license is exclusive at all.
- The remaining company: what happens to its contracts, customers and obligations after the team leaves.
- Exclusivity and non-solicit terms that restrict what the team or the startup can do after signing.
Founders should also ask counsel about merger-filing exposure for their own facts, since whether a deal is reportable turns on details no term sheet headline shows.
Pros and Cons for Each Side
An acquihire changes the position of four groups at once: the acquirer, the founders, the employees and the investors.
| Party | Upside | Risk |
|---|---|---|
| Acquirer | A working team and licensed technology without buying the whole company | Merger scrutiny if the package is a merger in substance; integration and retention risk |
| Founders | A defined outcome and a role at the buyer | A small payout after investor claims; a company left behind |
| Employees | A new offer, and in some deals accelerated vesting, as Cognition describes | Retention conditions, vesting resets, or staying with the shell company |
| Investors | A return where the startup might not otherwise reach an exit | A payout capped by the liquidation preference stack or a license that leaves little value in the shell |
Whether an acquihire is a bad outcome depends on the payout terms and on what the team wants: a founder who needs a home for a research team may be well served, while an employee holding unvested equity may not be. A related platform concern, how platforms favor their own products, has its own explainer.
Frequently Asked Questions
What is the difference between an acquihire and an acquisition?
An acquisition transfers a whole business to the buyer, while an acquihire mainly transfers the people, and the product and customers may stay behind. Cognition's announcement of its Windsurf deal describes a full acquisition, because it covers the IP, product, trademark and brand as well as the staff. A talent deal such as Microsoft and Inflection sits between the two: the CMA case page shows that hiring a team plus related arrangements was still assessed as a merger.
What does acqui-hiring mean?
Acqui-hiring means buying or partnering with a startup mainly to hire its team rather than to own its product or customer base. The label is informal, and regulators look at what the buyer actually acquires, not at what the deal is called. The CMA's Microsoft and Inflection decision, for example, asked whether the team and the assets it came with formed a business.
Can you give some examples of acqui-hiring?
Two recent examples come from the companies' own announcements. Microsoft said on March 19, 2024 that Mustafa Suleyman and Karén Simonyan were joining Microsoft AI, per Microsoft's announcement. On December 24, 2025, Groq announced a non-exclusive licensing agreement with Nvidia under which its founder Jonathan Ross, its president Sunny Madra and other team members would join Nvidia. Cognition's purchase of Windsurf is a contrasting full acquisition, covered in its own announcement.
Does an acquihire need regulatory approval?
It depends on whether the deal counts as a merger under local law and whether the filing thresholds are met. The European Commission said in its September 18, 2024 press release that the Microsoft and Inflection agreements amounted to a concentration but did not reach the EU notification thresholds and were not notified in any Member State, while the CMA reviewed the deal and announced a clearance decision on September 4, 2024. This is general information, not legal advice.
What happens to unvested equity in an acquihire?
The deal documents and each employee's new offer decide it, so treatment varies from one acquihire to the next. In Cognition's Windsurf announcement, the company said it waived vesting cliffs and fully accelerated vesting to date for every Windsurf employee. Read the offer letter and ask what happens to unvested equity before signing, and treat this as general information rather than legal advice.